
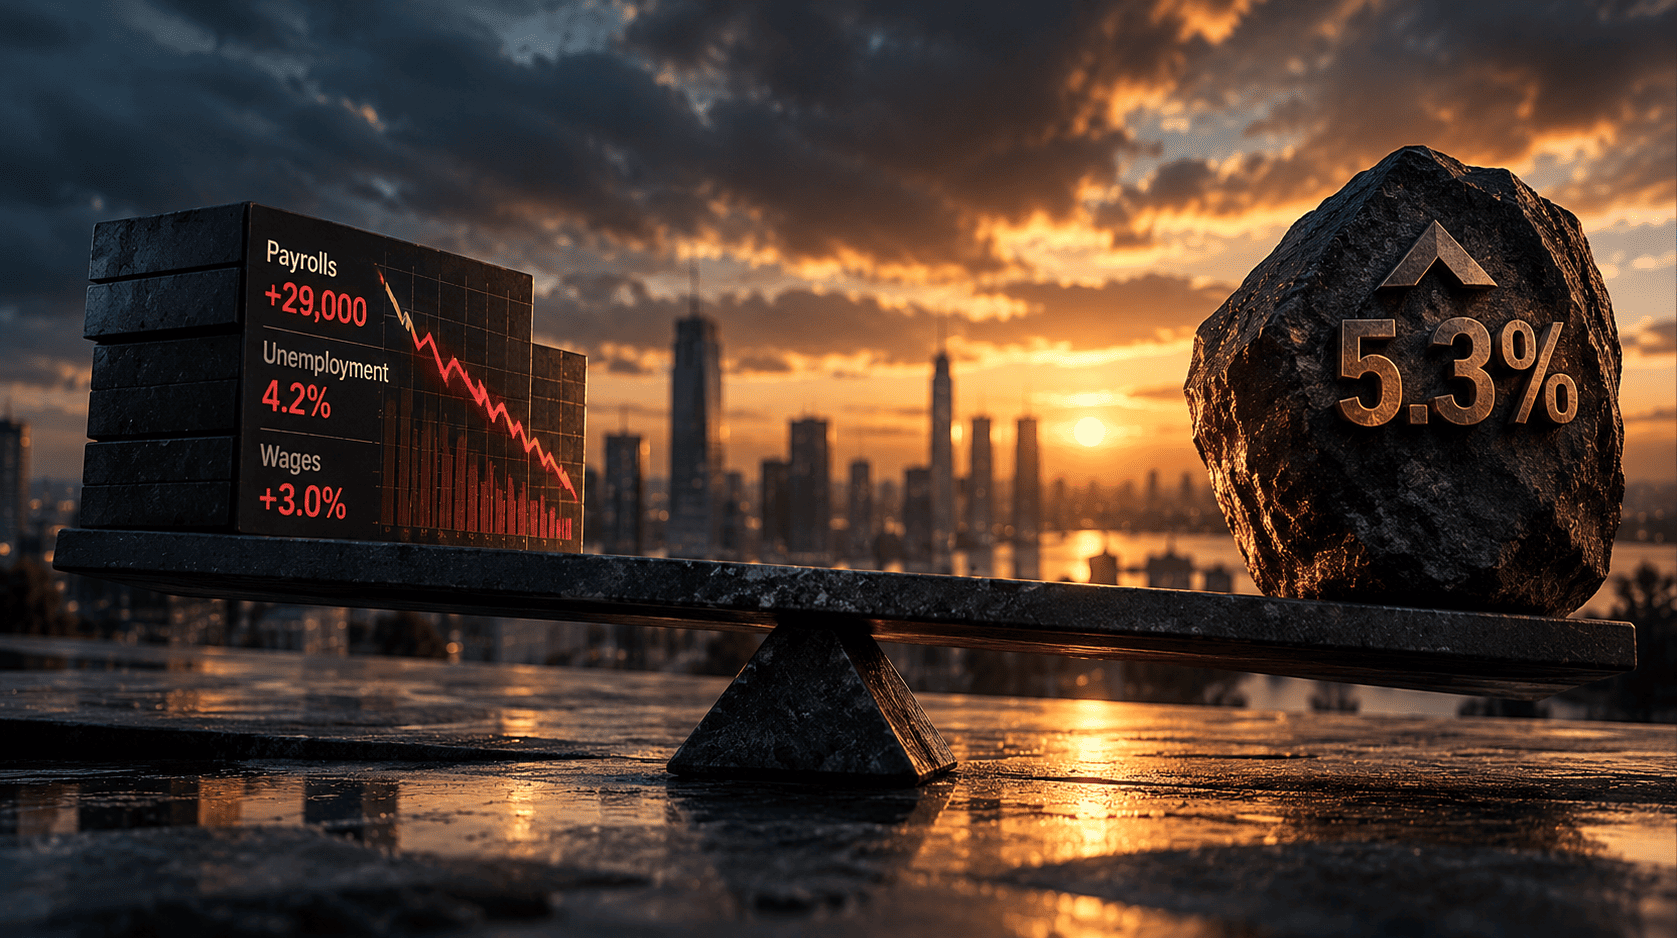
Softer US employment strengthened the case for a Federal Reserve pause. Elevated long-term yields, AI funding requirements and private-credit withdrawal demand show why financing conditions remain demanding.
This global market update examines five developments shaping the weekend outlook: weaker US payrolls, persistent Treasury yields, AI revenue requirements, private-credit liquidity, emergency oil reserves and Brazil’s election.
The central signal is the gap between monetary-policy expectations and the long-term cost of capital.
US employment growth slowed sharply in September. Treasury yields initially declined, then reversed much of that move. A potential Federal Reserve pause therefore offered limited reassurance to investors financing long-duration assets.
For private credit, property and AI infrastructure, the relevant question remains whether cash generation can support obligations while refinancing stays expensive.
Global markets at a glance
| Development | Key signal | Why it matters |
|---|---|---|
| US employment and bonds | Payrolls rose 29,000; the 10-year Treasury yield returned toward 5.3% | Softer hiring does not guarantee cheaper long-term financing |
| AI investment | Bain estimates a substantial new-revenue requirement | Monetisation must be assessed against infrastructure spending |
| Private credit | Blue Owl withdrawal requests remained above repurchase capacity | Fund liquidity requires separate assessment from loan quality |
| Energy | G7 agreed to a 100-million-barrel reserve release | Delivery can provide relief while supply constraints persist |
| Brazil | Presidential voting takes place on 4 October | Fiscal policy and political outcomes may affect local markets |
1. Weak US payrolls did not deliver sustained bond relief
US nonfarm payrolls increased by 29,000 in September, while unemployment edged up to 4.2%. August employment growth was revised down to 133,000.
Average hourly earnings rose 0.1% over the month and 3.0% over the year. The report indicated slower hiring and more moderate wage growth, although one monthly release does not establish a recession. 2026 M09 Results
The 10-year Treasury yield initially fell to approximately 5.16%, before returning toward 5.3%. Equities advanced as investors reassessed the likelihood of another near-term Federal Reserve increase.
Why it matters for financing costs
The policy rate and long-term bond yields respond to overlapping but different forces.
Employment data can change expectations for the Fed. Longer yields also reflect inflation expectations, government issuance, investor demand and compensation for holding duration.
Friday’s reversal is consistent with those competing pressures. It does not, by itself, establish which factor dominated or prove a permanent change in market behaviour.
Manhattan interpretation
A policy pause would prevent an additional immediate increase in the benchmark rate. It would not automatically reduce existing floating-rate payments or long-term refinancing costs.
Borrowers with strong current cash flow, manageable leverage and limited refinancing dependence are better positioned to absorb that uncertainty.
Watch: Inflation releases, Treasury auctions, real yields, credit spreads and subsequent labour-market data.
Sources: BLS — September 2026 employment report; Reuters — US hiring and the policy outlook; The Wall Street Journal — Treasury yields reverse their decline.
2. AI infrastructure faces a revenue-conversion test
AI investment is increasingly being assessed against the revenue required to justify its cost.
Reuters reports that Bain estimates more than US$4.2 trillion of new revenue may be required within five years to support the expanding infrastructure programme. This is a model-based estimate, rather than booked revenue or a fixed contractual funding gap.
The broader question is timing. AI can generate significant economic value while particular infrastructure owners earn disappointing returns if revenue arrives after financing payments, equipment replacement or refinancing deadlines.
Why it matters for AI credit
The spending cycle reaches beyond software into semiconductors, data centres, power, cooling, construction and equipment finance.
Investors need to distinguish revenue from external customers from funding supplied by shareholders, strategic partners or suppliers. Each can support growth, but they have different implications for repayment capacity.
Manhattan interpretation
Contracted demand improves visibility. Its credit value still depends on customer strength, pricing, termination rights and actual cash collection.
Senior claims and guarantees can strengthen protection, but they do not assure outperformance or eliminate utilisation and technology risk.
Watch: Operating cash flow, enterprise renewals, compute pricing, utilisation, capital expenditure and infrastructure-payment schedules.
Source: Reuters — AI investment and the revenue challenge.
3. Private-credit withdrawal demand remains uneven
Blue Owl’s two non-traded private-credit funds received approximately US$4.2 billion of third-quarter withdrawal requests, down from US$4.7 billion in the previous quarter.
Requests at Blue Owl Credit Income Corp represented 16.8% of shares. At the technology-focused Blue Owl Technology Income Corp, requests represented 39%.
Both funds offered customary repurchase capacity of 5%, subject to their tender terms. Most requests were resubmissions.
Goldman Sachs’ GS Credit fund presented a different picture: requests representing approximately 2% of shares and roughly US$400 million of gross subscriptions.
Why it matters for private-credit liquidity
The comparison demonstrates different fund-level liquidity conditions. It does not independently establish differences in loan quality or explain the cause of investor withdrawals.
Portfolio concentration, investor composition, distribution channels and new subscriptions can all influence demand for cash.
Repeated tenders indicate unmet withdrawal demand. They do not create a guaranteed first-in, first-out queue or assure completion by a particular date.
Manhattan interpretation
Investors should assess the portfolio and the withdrawal structure separately.
Repurchase limits can reduce pressure to sell assets quickly, while transferring exit-timing uncertainty to shareholders. Actual liquidity depends on repayments, cash resources, subscriptions, borrowing and any asset sales.
Watch: Repurchase fulfilment, new versus repeated requests, subscriptions, non-accrual loans, payment-in-kind income and financing used to support liquidity.
Sources: Reuters — Blue Owl withdrawal requests; Reuters — Goldman Sachs private-credit comparison.
4. G7 oil reserves provide a temporary supply bridge
G7 countries agreed on 2 October to coordinate the release of 100 million barrels of diesel and other reserves through the International Energy Agency.
The announcement offered potential relief to fuel markets. However, an agreement to release inventories is different from completed physical delivery. The timing, product mix and distribution of barrels will determine the immediate effect. www.reuters.com
US President Donald Trump also said he would not authorise a diesel-export ban, updating the earlier threat that had contributed to trade-policy uncertainty. www.reuters.com
Why it matters
Refined-product costs affect transport, agriculture, mining and construction. Emergency stocks can ease near-term pressure while broader shipping, refining and trade constraints remain.
For borrowers, delivered diesel and jet-fuel costs may matter more than movements in headline crude prices.
Manhattan interpretation
Reserve releases buy time. Their durability depends on whether normal supply improves before inventories require replenishment.
Lenders should continue testing margins and working-capital needs against adverse fuel-price scenarios.
Watch: Country-level release schedules, diesel allocation, refinery output, shipping conditions and Chinese export permissions.
Sources: Reuters — G7 reserve-release agreement; Reuters — US diesel-export policy.
5. Brazil’s election puts fiscal policy in focus
Brazil votes on 4 October, with President Luiz Inácio Lula da Silva and Senator Flávio Bolsonaro leading the contest.
A runoff is possible on 25 October if no candidate wins the required first-round majority. Polling scenarios are estimates of voter intentions, rather than election results.
Why it matters for emerging markets
Brazil is important to currency carry strategies, agriculture, mining and energy portfolios.
The result may affect expectations for government spending, debt sustainability and economic policy. Congressional composition and coalition support will influence how campaign proposals become legislation.
Manhattan interpretation
Fiscal credibility requires more than a favourable initial market reaction.
Investors should assess durable spending and revenue measures, institutional independence and the feasibility of implementation. Policy appointments may influence the outlook, but their effects depend on legal powers, approval procedures and the choices ultimately made.
Watch: First-round results, congressional seats, coalition negotiations, fiscal proposals, the real and local bond yields.
Sources: Reuters — Brazil election overview; Reuters — Datafolha runoff polling.
What these signals mean for private capital
The developments support a selective assessment of risk rather than a uniform conclusion about markets.
Weaker hiring may moderate monetary tightening. AI demand may support investment. Reserve releases may ease fuel costs. None independently guarantees affordable refinancing or sufficient investor returns.
Manhattan’s investment framework prioritises:
- Current cash generation and identifiable repayment sources.
- Conservative leverage and realistic refinancing assumptions.
- Contractual protections that remain enforceable under stress.
- Collateral values that account for depreciation and recovery costs.
- Liquidity terms aligned with the investor’s own cash needs.
These are analytical preferences, rather than confirmed evidence of a market-wide capital rotation.
The weekend and next-week watchlist
Brazil’s election and Middle East developments are the principal weekend catalysts.
Further evidence should come from reserve-release implementation, French fiscal negotiations and new disclosures on private-credit liquidity.
When markets reopen, Treasury yields and credit spreads will show whether Friday’s employment report produced lasting changes in financing expectations.
Trading hours also matter. Crypto markets operate continuously, while major bond, equity and currency markets reopen according to their respective schedules.
Manhattan view
A pause in monetary tightening is not a guarantee of cheaper capital.
The long-term financing hurdle depends on more than the next central-bank decision. Government borrowing, inflation expectations, investor demand and project-specific risk all influence the price of funding.
AI can create economic value without every financing structure earning an adequate return. Private credit can hold performing loans while investors face limited withdrawal capacity. Emergency inventories can relieve fuel pressure while supply constraints persist.
The strongest structure is the one that can withstand the delay between expected growth and realised cash flow.
Structure first. Yield second. Access only matters when the structure survives the downside case.
Stay informed. Stay liquid. Move first.
Learn more at manhattanprivatecredit.com.
General financial information and commentary only. This material does not constitute personal financial, investment, legal or tax advice, an offer of securities or a recommendation to transact. Analysis reflects information available as of 3 October 2026. Market prices, forecasts and financing conditions may change.