France sovereign risk is becoming a more important input in European credit pricing. Rising French government bond yields are challenging assumptions about the safety of core euro-area debt, with implications for bank funding, corporate refinancing and private-market valuations.
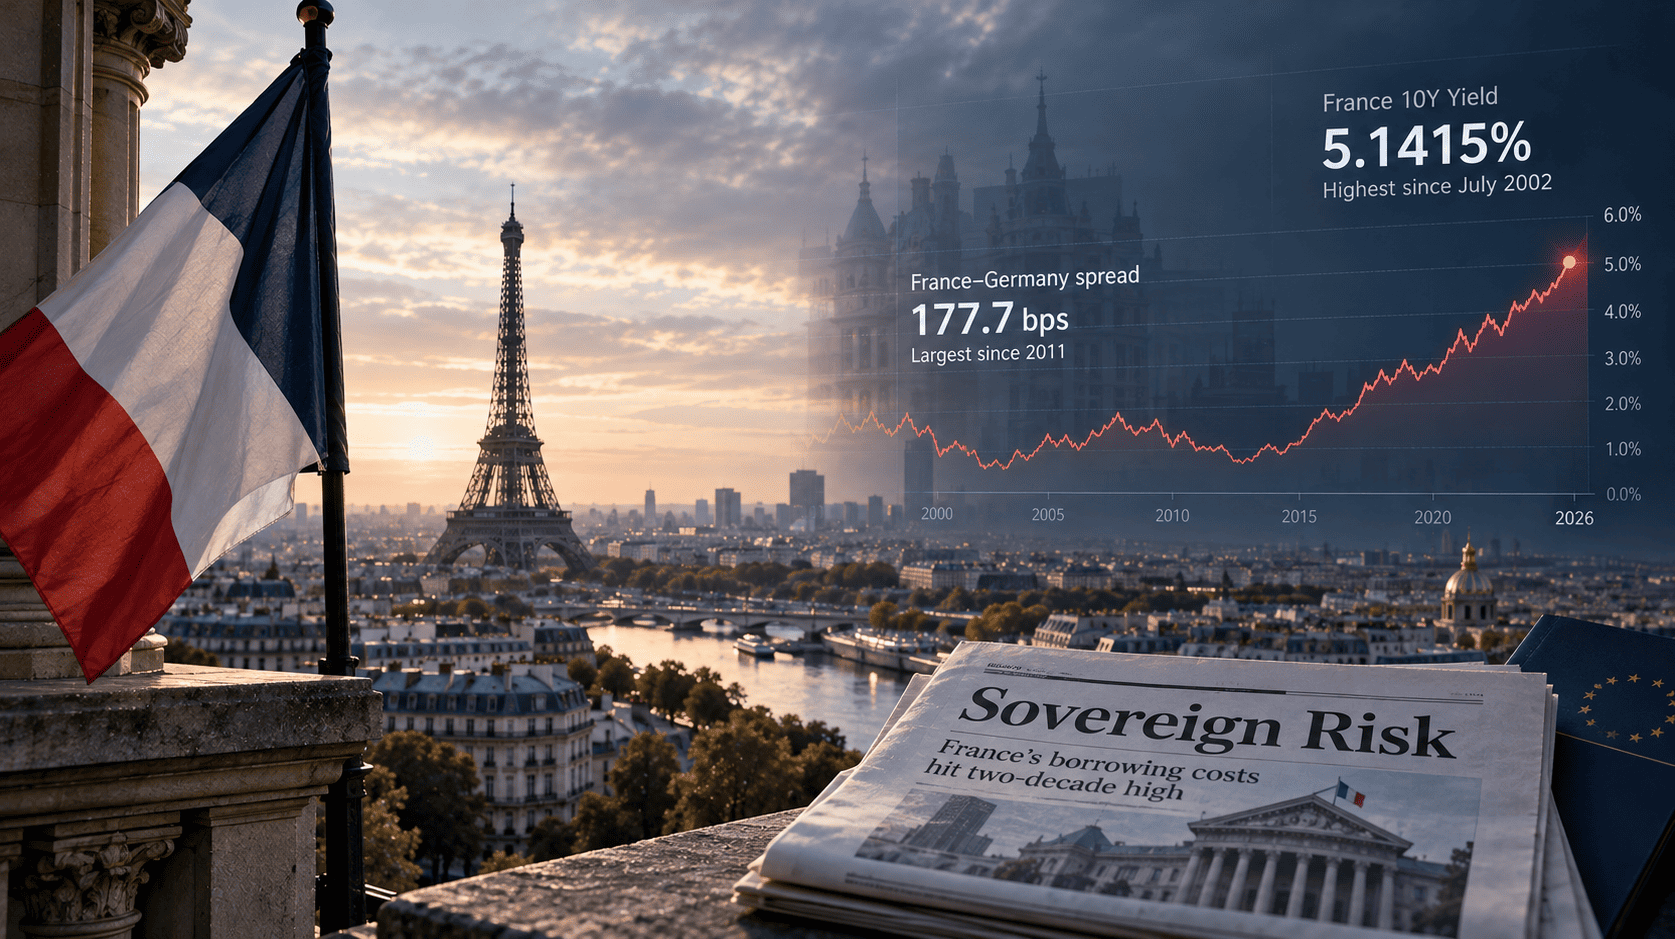
On 22 October, France’s 10-year government bond yield reached 5.1415%, its highest level since 2002. The premium over equivalent German Bunds widened to 177.7 basis points, returning to levels last seen during the 2011 euro-area sovereign debt crisis. Political uncertainty and fiscal concerns weighed on French debt as investors sought safety in German bonds.
These developments do not establish that France faces an imminent default. They do, however, raise a broader question: how should investors value European assets when a major sovereign borrower commands a substantially higher risk premium?
Why France sovereign risk is rising
France’s debt burden helps explain why confidence matters so much. According to INSEE, general government debt reached €3.5955 trillion at the end of the second quarter of 2026, equivalent to 119.0% of GDP. That compares with 117.5% three months earlier. Gross debt increased by €59.6 billion during the quarter, while net debt rose by €68.2 billion.
At the same time, France must maintain access to a large pool of buyers. Agence France Trésor’s indicative 2026 financing programme provides for €310 billion of medium- and long-term issuance, net of buybacks. This issuance figure is distinct from the government’s total financing requirement.
The analytical concern is the interaction between debt supply and investor confidence. A large financing programme becomes more expensive when buyers demand greater compensation for fiscal uncertainty. Higher yields then feed into debt-service costs as the government issues new securities and refinances maturing obligations.
This adjustment takes time. A rise in market yields does not immediately reprice the entire outstanding debt stock. Nevertheless, sustained borrowing pressure can progressively reduce fiscal flexibility.
How French government bond yields affect credit markets
Sovereign stress reaches the financial system through asset values, collateral and financing costs. When government bond yields rise, the market prices of existing fixed-rate bonds generally fall. Institutions holding those securities may face valuation losses, although the effect on reported earnings and regulatory capital depends on accounting treatment, hedging and portfolio classification.
Collateral is another transmission channel. Falling bond prices can reduce the amount of financing available against pledged assets. In stressed conditions, lenders may also require larger collateral buffers. These pressures are possible consequences of a prolonged sell-off, rather than automatic outcomes of every increase in sovereign yields.
Corporate borrowing costs can respond as well. French companies finance themselves against government, swap and other market benchmarks, with additional spreads reflecting their own credit risk. A higher sovereign premium can therefore influence funding conditions even when a company’s operating performance remains stable.
For banks, more expensive wholesale funding and greater balance-sheet uncertainty may encourage tighter lending standards. That can affect loan maturity, leverage, collateral requirements and covenant protection.
What higher sovereign risk means for European private credit
European private credit could receive additional financing requests if banks become more selective. Borrowers may seek direct loans, asset-backed financing or alternative refinancing arrangements when conventional credit becomes harder to secure.
However, greater demand does not automatically improve investment quality. Private lenders still face the same borrower cash flows, asset values and refinancing constraints that concern public-market investors. A higher coupon may compensate for greater risk, but it does not remove that risk.
Three questions become particularly useful when assessing a transaction: can the borrower service debt under more demanding financing conditions, does the collateral retain sufficient value under stress, and can the capital structure survive a delayed refinancing or exit?
Documentation also matters. Covenant headroom, reporting obligations, security enforceability and restrictions on asset transfers can influence recoveries when conditions deteriorate. The opportunity lies in financing resilient borrowers on appropriate terms, rather than treating reduced bank competition as evidence of safety.
Can the ECB contain sovereign market stress?
The European Central Bank’s Transmission Protection Instrument, or TPI, provides a mechanism to address disorderly financing conditions that threaten monetary-policy transmission. Its framework targets deterioration not justified by country-specific fundamentals, and purchases are not subject to a predetermined size limit.
Activation remains discretionary. The ECB assesses market conditions alongside fiscal sustainability, compliance with the EU fiscal framework, macroeconomic imbalances and policy commitments.
For investors, the implication is that the existence of a backstop should not be treated as a guarantee of intervention at a particular bond spread. Distinguishing market dysfunction from a justified reassessment of fiscal risk remains central to the policy decision.
That distinction also limits the investment case for relying on central-bank support alone. A financing structure needs to remain viable across a range of policy responses.
How sovereign repricing affects private-market valuations
Higher required returns can place pressure on property, infrastructure and buyout valuations. If investors demand a larger premium for holding French assets, acquisition prices and exit assumptions may need to adjust.
The impact varies by transaction. Long-term contracted revenue can support cash-flow visibility, while floating-rate debt, near-term maturities and refinancing dependence can increase vulnerability. Inflation-linked income may provide protection, but its value depends on contractual terms, adjustment timing and operating costs.
Private valuations can also adjust more slowly than publicly traded bond prices. An unchanged reported net asset value does not necessarily mean the asset’s economic value is unchanged. Updated discount rates, comparable transactions and financing assumptions may reveal pressure before formal valuations reflect it.
For NAV-backed facilities, the relevant analysis includes valuation sensitivity, covenant headroom and lender rights following a decline in collateral value.
What Manhattan is watching
The France-Germany bond spread remains an important indicator, but it should be assessed alongside evidence from funding markets and borrower behaviour. Manhattan is monitoring:
- French sovereign auctions, including demand, pricing and bid-to-cover ratios.
- Funding spreads for French banks, covered bonds and investment-grade companies.
- Signs of sovereign spread pressure extending to Italy and Spain.
- ECB communication on fragmentation and TPI eligibility.
- Changes in private lending terms, valuation assumptions and NAV facility headroom.
A sustained deterioration across these indicators would suggest a broader tightening in financing conditions. Stabilising spreads and resilient auction demand would support a more contained interpretation.
Manhattan’s view on France sovereign risk
France sovereign risk matters because sovereign credibility influences financing conditions well beyond government debt. A persistent increase in the required risk premium can affect corporate borrowing, bank lending and the returns investors demand from private assets.
The practical response is to reassess financing assumptions. Underwriting should consider wider sovereign and credit spreads, delayed exits, lower collateral values and reduced refinancing availability. Higher yields deserve attention only alongside the cash flows and protections supporting them.
France’s bond repricing is therefore a reminder to examine how each investment is funded, valued and protected. In European private credit, structure remains the starting point for evaluating yield.
Learn more at manhattanprivatecredit.com.
This material provides general financial information. It does not constitute personal financial, legal or investment advice, or an offer or recommendation to acquire any security. Markets and private investments involve risk, including loss of capital.