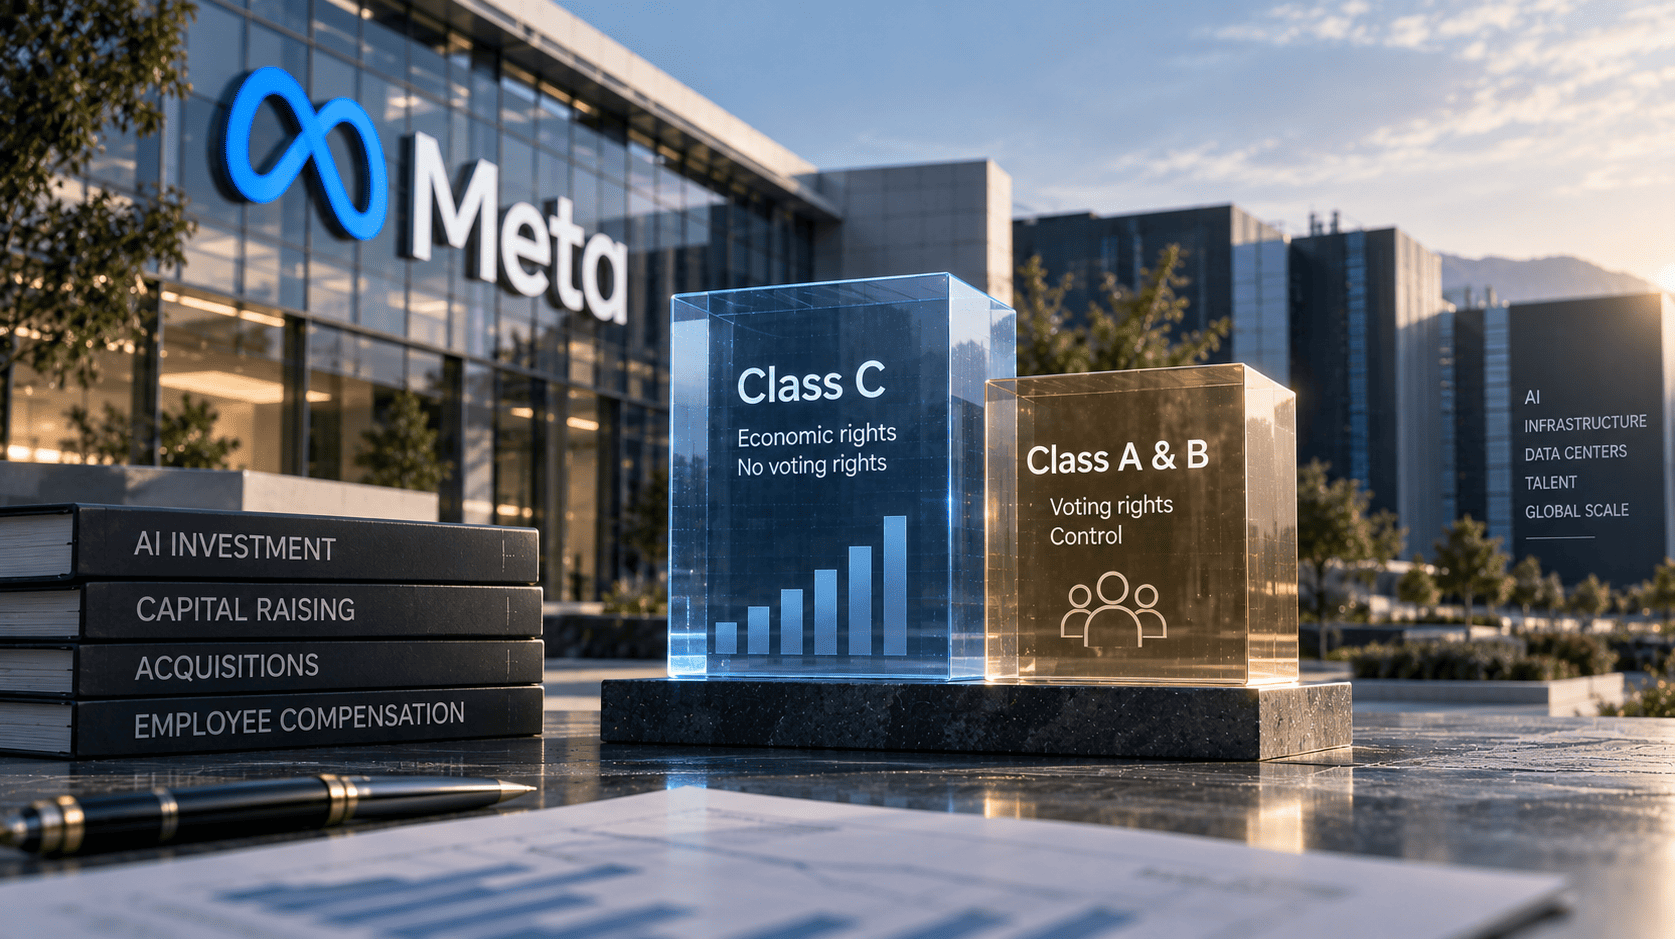
Meta Class C shares would give the company a new way to finance expansion while preserving Mark Zuckerberg’s voting control. The approved structure creates a non-voting share class that Meta could use to raise capital, compensate employees and fund acquisitions as its artificial-intelligence investment programme grows.
The distinction is between economic ownership and decision-making power. Investors receiving newly issued Class C shares would participate in Meta’s financial performance without receiving corresponding ordinary voting rights. Existing shareholders could therefore experience economic dilution from future issuance even while the distribution of voting power remains unchanged.
For investors, the announcement raises two connected questions: how much financing flexibility the new shares provide, and how effectively shareholders can influence the use of that capital.
What Meta has approved
Meta’s board approved the Class C structure following a unanimous recommendation from a special committee of disinterested and independent directors. The company intends the amended charter establishing the class to become effective on 19 January 2027.
The board also declared a conditional stock dividend of one Class C share for each outstanding Class A and Class B share. Record and payment dates will be set later, and Meta intends to seek a Nasdaq listing for Class C upon issuance. The charter amendment has received shareholder approval through written consent. prnewswire.com
This establishes a financing option rather than announcing a completed capital raise. Meta has not specified the size, price or timing of a subsequent Class C offering or acquisition financed with the new stock.
How Meta Class C shares separate ownership from control
Meta’s existing share structure already separates economic ownership from voting influence. Class A shares carry one vote per share, while Class B shares carry superior voting rights that concentrate control with Zuckerberg. Class C would add economic participation without ordinary voting rights.
That gives Meta another currency for corporate transactions. It could issue stock to acquisition sellers, grant shares to employees or sell shares to investors without issuing an equivalent amount of voting power.
The initial distribution and later issuance have different effects. A proportionate stock dividend does not itself bring new cash into Meta or automatically increase an investor’s wealth. Share prices should adjust to reflect the additional securities and their respective rights.
Subsequent issuance to outside investors, employees or acquisition sellers can reduce existing holders’ percentage economic ownership, all else equal. Whether a transaction increases or reduces value per share then depends on what Meta receives in return and the returns generated by that capital.
The structure preserves voting control more directly than it protects per-share economics.
Why AI spending makes financing flexibility valuable
The financial backdrop helps explain the strategic appeal. Meta reported third-quarter revenue of US$64.60 billion, up 26% year on year. Capital expenditure, including principal payments on finance leases, reached US$34.91 billion, while free cash flow was negative US$2.12 billion.
Meta narrowed its full-year 2026 capital-expenditure outlook to US$135 billion–US$145 billion from US$130 billion–US$145 billion. It also reported US$82.45 billion of cash, cash equivalents and marketable securities at 30 September. prnewswire.com
These figures describe a profitable operating business undertaking substantial investment. Negative free cash flow for one quarter does not establish financial distress. It does show why management may value more options for financing infrastructure, acquisitions and compensation.
New equity could preserve cash or reduce reliance on additional borrowing. However, creating a share class does not guarantee that investors will provide capital on attractive terms. The usefulness of Class C will depend on market demand, valuation and the company’s decisions about issuance.
What non-voting shares mean for shareholders
The governance trade-off becomes clearest when capital-allocation decisions disappoint. Shareholders may bear the economic consequences of spending overruns, unsuccessful acquisitions or slower monetisation while having limited ability to change the company’s direction through voting.
Founder control can also support investment with a long payback period. Management may pursue infrastructure and research programmes that public investors would otherwise pressure it to reduce. Whether that produces attractive returns depends on execution, financial discipline and the eventual earnings generated.
Non-voting ownership still carries legal and economic rights under the applicable documents and law. It should not be confused with having no shareholder protections. Nevertheless, investors need to understand which decisions they can influence and which remain concentrated elsewhere.
The relevant assessment combines the financial claim, governance rights and price paid for the security.
Could Class C and Class A trade at different prices?
Separate listed share classes can develop different valuations because voting rights, liquidity and investor demand differ. Index eligibility, institutional mandates and the number of shares available for trading can also affect pricing.
A discount for non-voting shares is possible, but it is not guaranteed. A highly liquid Class C market could attract investors primarily seeking economic exposure, while other buyers may place greater value on Class A’s voting rights.
The initial distribution is therefore only the beginning of the market assessment. Investors will need to monitor trading conditions, future issuance and buybacks to understand how the classes interact over time.
Implications for creditors and AI infrastructure counterparties
From a credit perspective, an actual equity raise can strengthen a company’s funding position without creating the same scheduled principal repayments as debt. That could provide additional flexibility during a prolonged infrastructure investment cycle.
The benefit depends on how proceeds are used. Capital that supports productive assets or reduces borrowing can improve resilience. Capital committed to projects with uncertain returns may extend the spending cycle without improving future cash generation.
Suppliers, developers and acquisition targets could also benefit from another potential funding channel. Some may accept listed shares instead of cash, although doing so transfers share-price exposure to the recipient.
For private capital, the broader implication is that AI financing will continue to combine equity, debt, leases and project structures. Each allocates different risks, payment obligations and control rights.
Key risks investors should monitor
Economic dilution is the most direct risk from future issuance. A company can strengthen its balance sheet while reducing existing shareholders’ percentage ownership. Investors should assess the proceeds or assets received against the additional claims created.
Governance concentration is another consideration. Financing growth without equivalent voting dilution can reduce one constraint on management’s capital-allocation decisions. Independent oversight, disclosure and transaction terms consequently become more important.
Legal obligations also compete for financial resources. Meta’s quarterly release disclosed a US$9.89 billion charge related to an agreement with US state attorneys general. An accounting charge and the timing of cash payments are different, so investors should examine the payment schedule rather than treating the full expense as an immediate cash outflow.
Finally, financing flexibility does not resolve infrastructure execution risk. Power availability, construction schedules, equipment costs and the time required to monetise AI products remain central to investment returns.
What Manhattan is watching
Manhattan Private Network is monitoring the amended charter, information statement, Founder Alignment Agreement and Nasdaq listing details. These documents will clarify the rights attached to Class C and the conditions governing the structure.
The next financial signals are actual issuance, acquisition consideration, stock-based compensation and buybacks. Those actions will show whether Class C becomes an occasional transaction currency or a recurring source of funding.
Operating cash flow, capital expenditure, finance-lease payments and incremental depreciation will be equally important. The long-term test is whether the investment programme generates sufficient earnings and cash to justify the capital committed.
Manhattan view: financing capacity comes with a governance price
Meta Class C shares would expand the company’s financing options while preserving its existing concentration of voting authority. That could support a long investment horizon, but it places greater weight on management’s capital-allocation discipline.
Investors should assess the economic rights they receive, the influence attached to those rights and the terms of future issuance. The initial stock dividend changes the securities investors hold; subsequent financing decisions determine how the structure affects ownership and value.
Structure first. Yield second. Access only matters when the structure is worth accessing.
Sources
- Meta third-quarter 2026 results and Class C announcement, 21 October 2026.
- Reuters: Meta to issue new class of shares as it tightens AI spending forecast, 21 October 2026.
This publication is general financial information and analysis only. It is not personal financial advice, an offer or a recommendation. Markets involve risks including dilution, volatility and loss of capital.